Trusted Mortgage Advice in Cramlington
Looking for a mortgage broker in Cramlington? We help families, first-time buyers and homeowners across this Northumberland new town. You’ll get independent advice, with each step explained.
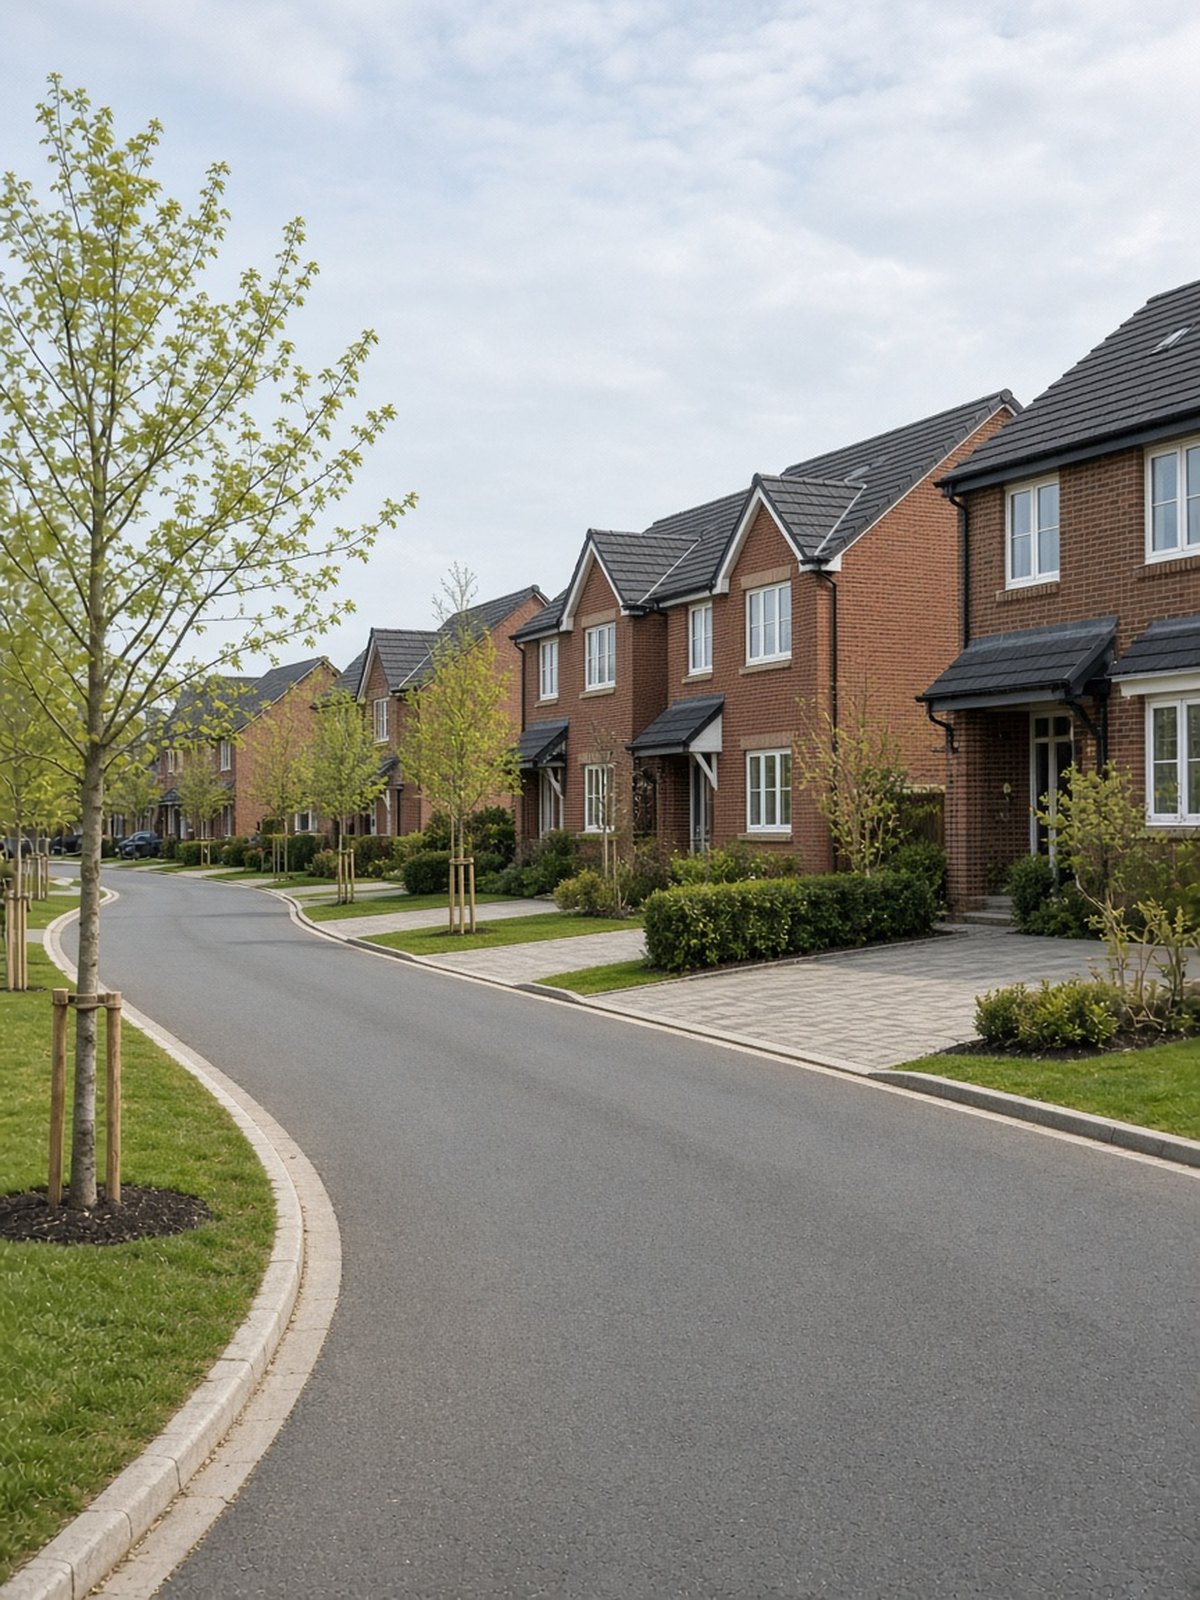
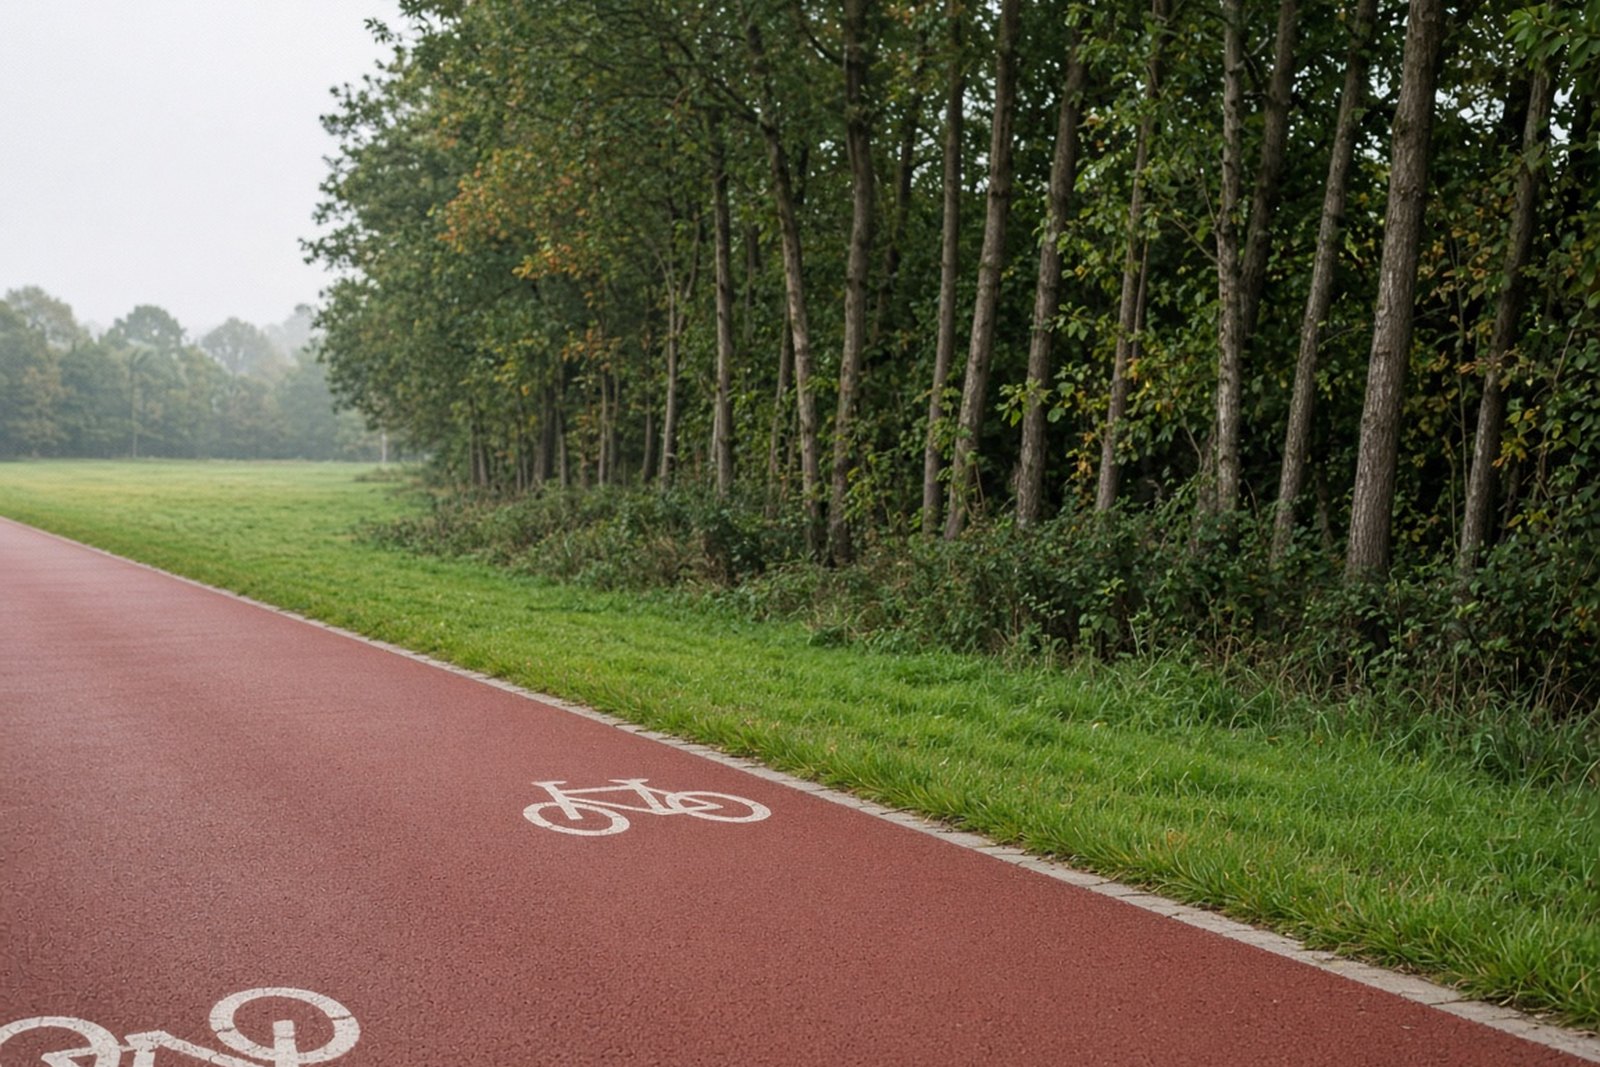
Cramlington was planned in the 1960s as a new township about six miles north of Newcastle. Around 29,000 people live in the built-up area. Semis and detached homes sit on curved estate roads near the A1 and the railway. Segregated cycle paths from the new-town design still run beside many estates.
Your Local Mortgage Broker in Cramlington
Our North East advisers cover south-east Northumberland from Gosforth. We can talk by phone or video, or meet at 40 Fawdon Lane. Book a free initial appointment to begin. Evening calls can often be arranged if daytime is difficult.
Cramlington station sits on the East Coast Main Line. Manor Walks and Concordia leisure centre serve the town centre. We also cover Morpeth, Whitley Bay and Backworth. Our Northumberland page lists more of the county.
Why Use a Mortgage Broker in Cramlington?
Free Mortgage Appointments for Every Customer
Estate homes near major roads and the railway attract commuting buyers. Offers can move quickly. A mortgage in principle ready beforehand helps. The first chat is free.
We’ll gather the paperwork, keep the lender updated and chase progress with your solicitor. You’ll always know where things stand. We’ll also explain any fees up front, so you know the full cost of the move.
Popular Mortgage Scenarios in Cramlington
Many moves here stay within the estates: a starter semi for a larger detached house. Others arrive from Newcastle or Morpeth for space and schools.
We’ll estimate the equity you’ll carry over and what you’ll need to borrow. We’ll check early repayment charges too. Then we’ll help both sides complete together. If you need to buy before your sale is agreed, we’ll explain how lenders view that.
Homes from the 1960s to the 1990s make up much of the stock. Lenders look at construction type and estate location. Commuting buyers often need firm offer timing.
We’ll choose lenders familiar with this age of housing. We’ll also watch offer expiry dates if you’re racing a reservation. MoneyHelper’s guide to buying a home covers surveys.
Smaller semis on the planned estates can make a good first home. We help first time buyers turn that plan into a realistic budget.
We’ll review your savings, income and outgoings in one go. Then we’ll show which lenders may fit and the documents each will ask for. We’ll also explain how deposit gifts from family need to be set out for lenders.
Road and rail links can support rental demand from people who work in Newcastle or on local industrial estates. A let mortgage works differently.
Lenders mostly judge the case on the expected rent. We’ll explain those checks and the deposit normally required. If you already own a rental property, we’ll look at how a new one fits alongside it.
A fixed or tracker period ends on a set date. If you do nothing, you’ll usually move onto the lender’s standard rate.
We’ll set staying with your lender against switching elsewhere. Want to borrow more or change the term? We’ll build that in and handle the forms. Then we’ll take the paperwork off your hands.
Don’t Just Take Our Word for It


Important information
Your home may be repossessed if you do not keep up repayments on your mortgage.